• Home
  • Insight
  • Blog
  • Business
  • Entertainment
  • Health
  • Politics
  • Shop
    • Gift Shop
    • Value Shop
    • Store
    • Bargain Shop
    • Discount
  • Sports
  • Tech
  • Travel
  • USA
  • Video
  • World
    • Asia
    • Africa
    • South America
    • North America
    • Europe
    • Oceania
Wednesday, October 7, 2026
No Result
View All Result
Subscribe Now
  • Home
  • Insight
  • Blog
  • Business
  • Entertainment
  • Health
  • Politics
  • Shop
    • Gift Shop
    • Value Shop
    • Store
    • Bargain Shop
    • Discount
  • Sports
  • Tech
  • Travel
  • USA

    Washington state man charged with helping Canadian mass shooter plan for attack

    Border Security, Public Safety, and American Sovereignty with Markwayne Mullin

    Students injured as NJ high school bleachers collapse in scary scene

    California man in incest case busted in Mexico; teen daughter rescued

    Cornell president calls gang rape allegations ‘deeply disturbing’ : NPR

    France’s violent student protests raise warning for America: ‘A cautionary tale’

    Birmingham’s WBHM Public Radio Station Forced to Use “Gulf of America”

    Eminem gets online backlash from fans over Kid Rock Christian album collab

    Trump leans into Iran war, admits it could cost Republicans the midterms

  • Video
  • World
    • Asia
    • Africa
    • South America
    • North America
    • Europe
    • Oceania
The Insight Post
  • Home
  • Insight
  • Blog
  • Business
  • Entertainment
  • Health
  • Politics
  • Shop
    • Gift Shop
    • Value Shop
    • Store
    • Bargain Shop
    • Discount
  • Sports
  • Tech
  • Travel
  • USA

    Washington state man charged with helping Canadian mass shooter plan for attack

    Border Security, Public Safety, and American Sovereignty with Markwayne Mullin

    Students injured as NJ high school bleachers collapse in scary scene

    California man in incest case busted in Mexico; teen daughter rescued

    Cornell president calls gang rape allegations ‘deeply disturbing’ : NPR

    France’s violent student protests raise warning for America: ‘A cautionary tale’

    Birmingham’s WBHM Public Radio Station Forced to Use “Gulf of America”

    Eminem gets online backlash from fans over Kid Rock Christian album collab

    Trump leans into Iran war, admits it could cost Republicans the midterms

  • Video
  • World
    • Asia
    • Africa
    • South America
    • North America
    • Europe
    • Oceania
No Result
View All Result
No Result
View All Result
Home Investing

The Mortgage Interest Deduction Is Overrated and Definitely Not Something to Fight Over

by Theinsightpost
May 5, 2024
in Investing
0 0
0
The Mortgage Interest Deduction Is Overrated and Definitely Not Something to Fight Over

After the National Association of Realtors agreed to pay $418 million and eliminate the 6% commission to settle the lawsuit against it, attention in some quarters is now being turned to the mortgage interest deduction. 

Given the wave of anti-real estate investor legislation, it would seem like the mortgage interest deduction is the next domino to fall. But not all “falls” are created equal. The fact of the matter is that the mortgage interest deduction is not particularly important. Removing it would have a negligible impact and is most certainly not a hill for real estate investors to die on.

For one, the mortgage interest deduction only amounts to a tax savings of around $30 billion a year (down from $60 billion after the Tax Cuts and Jobs Act of 2017). That may sound like a lot, but it’s important to put this in context:

So, in the end, the mortgage deduction is small potatoes. 

What the Mortgage Interest Deduction Is, and What Eliminating Would Do

The mortgage interest deduction simply allows homeowners who itemize their deductions to deduct interest payments on up to $750,000 of their loan principal. (It was $1 million until the Tax Cuts and Jobs Act of 2017.) 

This is not actually a particularly large deduction. Remember, the standard deduction is $14,600 for single filers and $29,200 for married couples filing jointly in 2024. 

Most homeowners still have mortgages that were taken out before rates skyrocketed in mid-2022. So, for example, if someone has a $750,000 loan amortized over 30 years at 3% interest, the annual mortgage interest would only amount to $22,809.59, which is actually less than the jointly filed standard deduction. But even on a $750,000 loan amortized over 30 years at 7% interest, it only amounts to $52,258.65 of interest in year one (and less every year thereafter).  

In the highest tax bracket as of this writing (37%) that would amount to saving $19,335.70 on one’s taxes versus just $10,804 for the standard deduction for those filing jointly. That amounts to a savings of $9,335.70. Not bad, but nothing to write home about.

This is why it shouldn’t be surprising that the mortgage interest deduction only results in $30 billion of savings each year, or about 0.68% of what the federal government collects in tax revenue.

Now, if someone has multiple other deductions like charitable donations or medical expenses, the total savings from the mortgage interest deduction in the previous example could be as much as $19,335.70 over and above the standard deduction. But the only people saving this amount would be affluent.   

This is the primary criticism of the mortgage interest deduction, namely that it amounts to a regressive tax (or tax break, to be precise), which is the key point its critics make. As Katheryn Anne Edwards tells Bloomberg:

“The policy’s weakness is exposed by who benefits. The only households that can claim the deduction are those that itemize expenses, and they are predominantly in higher income tax brackets. This cohort generally doesn’t need to rely on the deduction to buy a home and service the mortgage, so it only serves to push up the amount of debt they can take on and, as a result, home prices at the middle and top ends of the market.”

Distribution of mortgage interest tax deduction expenditure by income class (2020) – Bloomberg

Edwards believes it is at least likely that “doing away with the mortgage interest deduction is an actionable policy the federal government can take” to improve home affordability. This is highly doubtful, as the policy has a negligible effect overall, and housing prices are being driven by increased demand without a corresponding increase in supply. Indeed, cutting the total savings to taxpayers from the mortgage interest deduction in half after the 2017 tax cut certainly didn’t slow real estate price appreciation in the slightest.

Correspondingly, it’s quite clear that there isn’t much, if any, economic benefit to having the mortgage tax deduction. As a subsidy for homeownership, it doesn’t make a lot of sense, given it generally benefits wealthier people who generally don’t have a problem buying a home in the first place. In short, helping affluent people who should be buying homes worth $650,000 to instead buy homes worth $700,000 should not be a pressing government concern.

And as a stimulus to the housing market, it’s also completely unnecessary, as housing is almost as expensive as it has ever been. If anything, we have the opposite problem. 

Studies tend to show very small and generally negative effects. A study by the nonpartisan Tax Policy Center found that the 2017 changes to the mortgage interest deduction had a very minimal effect that was completely offset by the same law’s tax reduction. 

Another study from Denmark found that “the mortgage deduction has a precisely estimated zero effect on homeownership for high– and middle-income households.” An international survey found that “the empirical evidence suggests that, contrary to popular wisdom, the [mortgage interest deduction] generally does not increase the ownership rate.” 

If anything, removing the mortgage interest deduction would likely have a slightly positive effect. A study in the American Economic Review found that “eliminating the mortgage interest deduction causes house prices to decline, increases homeownership, decreases mortgage debt, and improves welfare.” 

But as the charts in the study show, the effects, while significant, are tiny.

 Home and rent price transition after elimination of mortgage interest deduction - Kamila Sommer and Paul Sullivan, “Implications of US Tax Policy for House Prices, Rents, and Homeownership,” American Economics Review
Home and rent price transition after elimination of mortgage interest deduction – Kamila Sommer and Paul Sullivan, “Implications of US Tax Policy for House Prices, Rents, and Homeownership,” American Economics Review

Kamila Sommer and Paul Sullivan, “Implications of US Tax Policy for House Prices, Rents, and Homeownership,” American Economics Review, Pg. 265

What About Real Estate Investors?

Some might be concerned that removing the mortgage interest deduction would severely affect real estate investors. After all, the tax advantages of owning real estate are one of the biggest boons to property ownership there is. Fortunately, this is not an issue with real estate investments.

As the IRS website states, “You can deduct the ordinary and necessary expenses for managing, conserving and maintaining your rental property… Necessary expenses are those that are deemed appropriate, such as interest, taxes, advertising, maintenance, utilities and insurance.” 

There’s no $750,000 limit, either. As the National Association of Realtors points out, “[U]nlike those who itemize mortgage interest deductions, rental property owners are not subject to a limit on the amount of the debt.”

And why should there be? Real estate investment is a business, and every other business is allowed to deduct their business interest expense from their taxable income (with some exceptions). It would be completely unfair to single out real estate investment as an exception.

Final Thoughts

Indeed, that is probably the best case to make for why a mortgage interest deduction for homeowners should stay on the books: Why should real estate investors benefit from a tax deduction that homeowners do not? 

For this reason and the (very) marginal boon it grants to the housing market, the National Association of Realtors has “strongly opposed” any attempt to reduce or eliminate it.

But as noted, the cost to the real estate market would be tiny if it were to go. Furthermore, the homeowners who tended to be affected would be the wealthier among us, and even for them, only to a slight degree.

If we want to subsidize homeownership, tax credits for lower-income people would make far more sense. The mortgage interest deduction has proven to be an ineffective and mostly irrelevant tool to aid the housing market. For most of us, it would not be missed.

Get the Best Loan Today

Find trusted, investor-friendly lenders who specialize in your strategy.

investor friendly lender, investor friendly real estate loans

Ready to succeed in real estate investing? Create a free BiggerPockets account to learn about investment strategies; ask questions and get answers from our community of +2 million members; connect with investor-friendly agents; and so much more.

Note By BiggerPockets: These are opinions written by the author and do not necessarily represent the opinions of BiggerPockets.
ShareTweetSend
Previous Post

TJ Martin – BOOOOOOOM! – CREATE * INSPIRE * COMMUNITY * ART * DESIGN * MUSIC * FILM * PHOTO * PROJECTS

Next Post

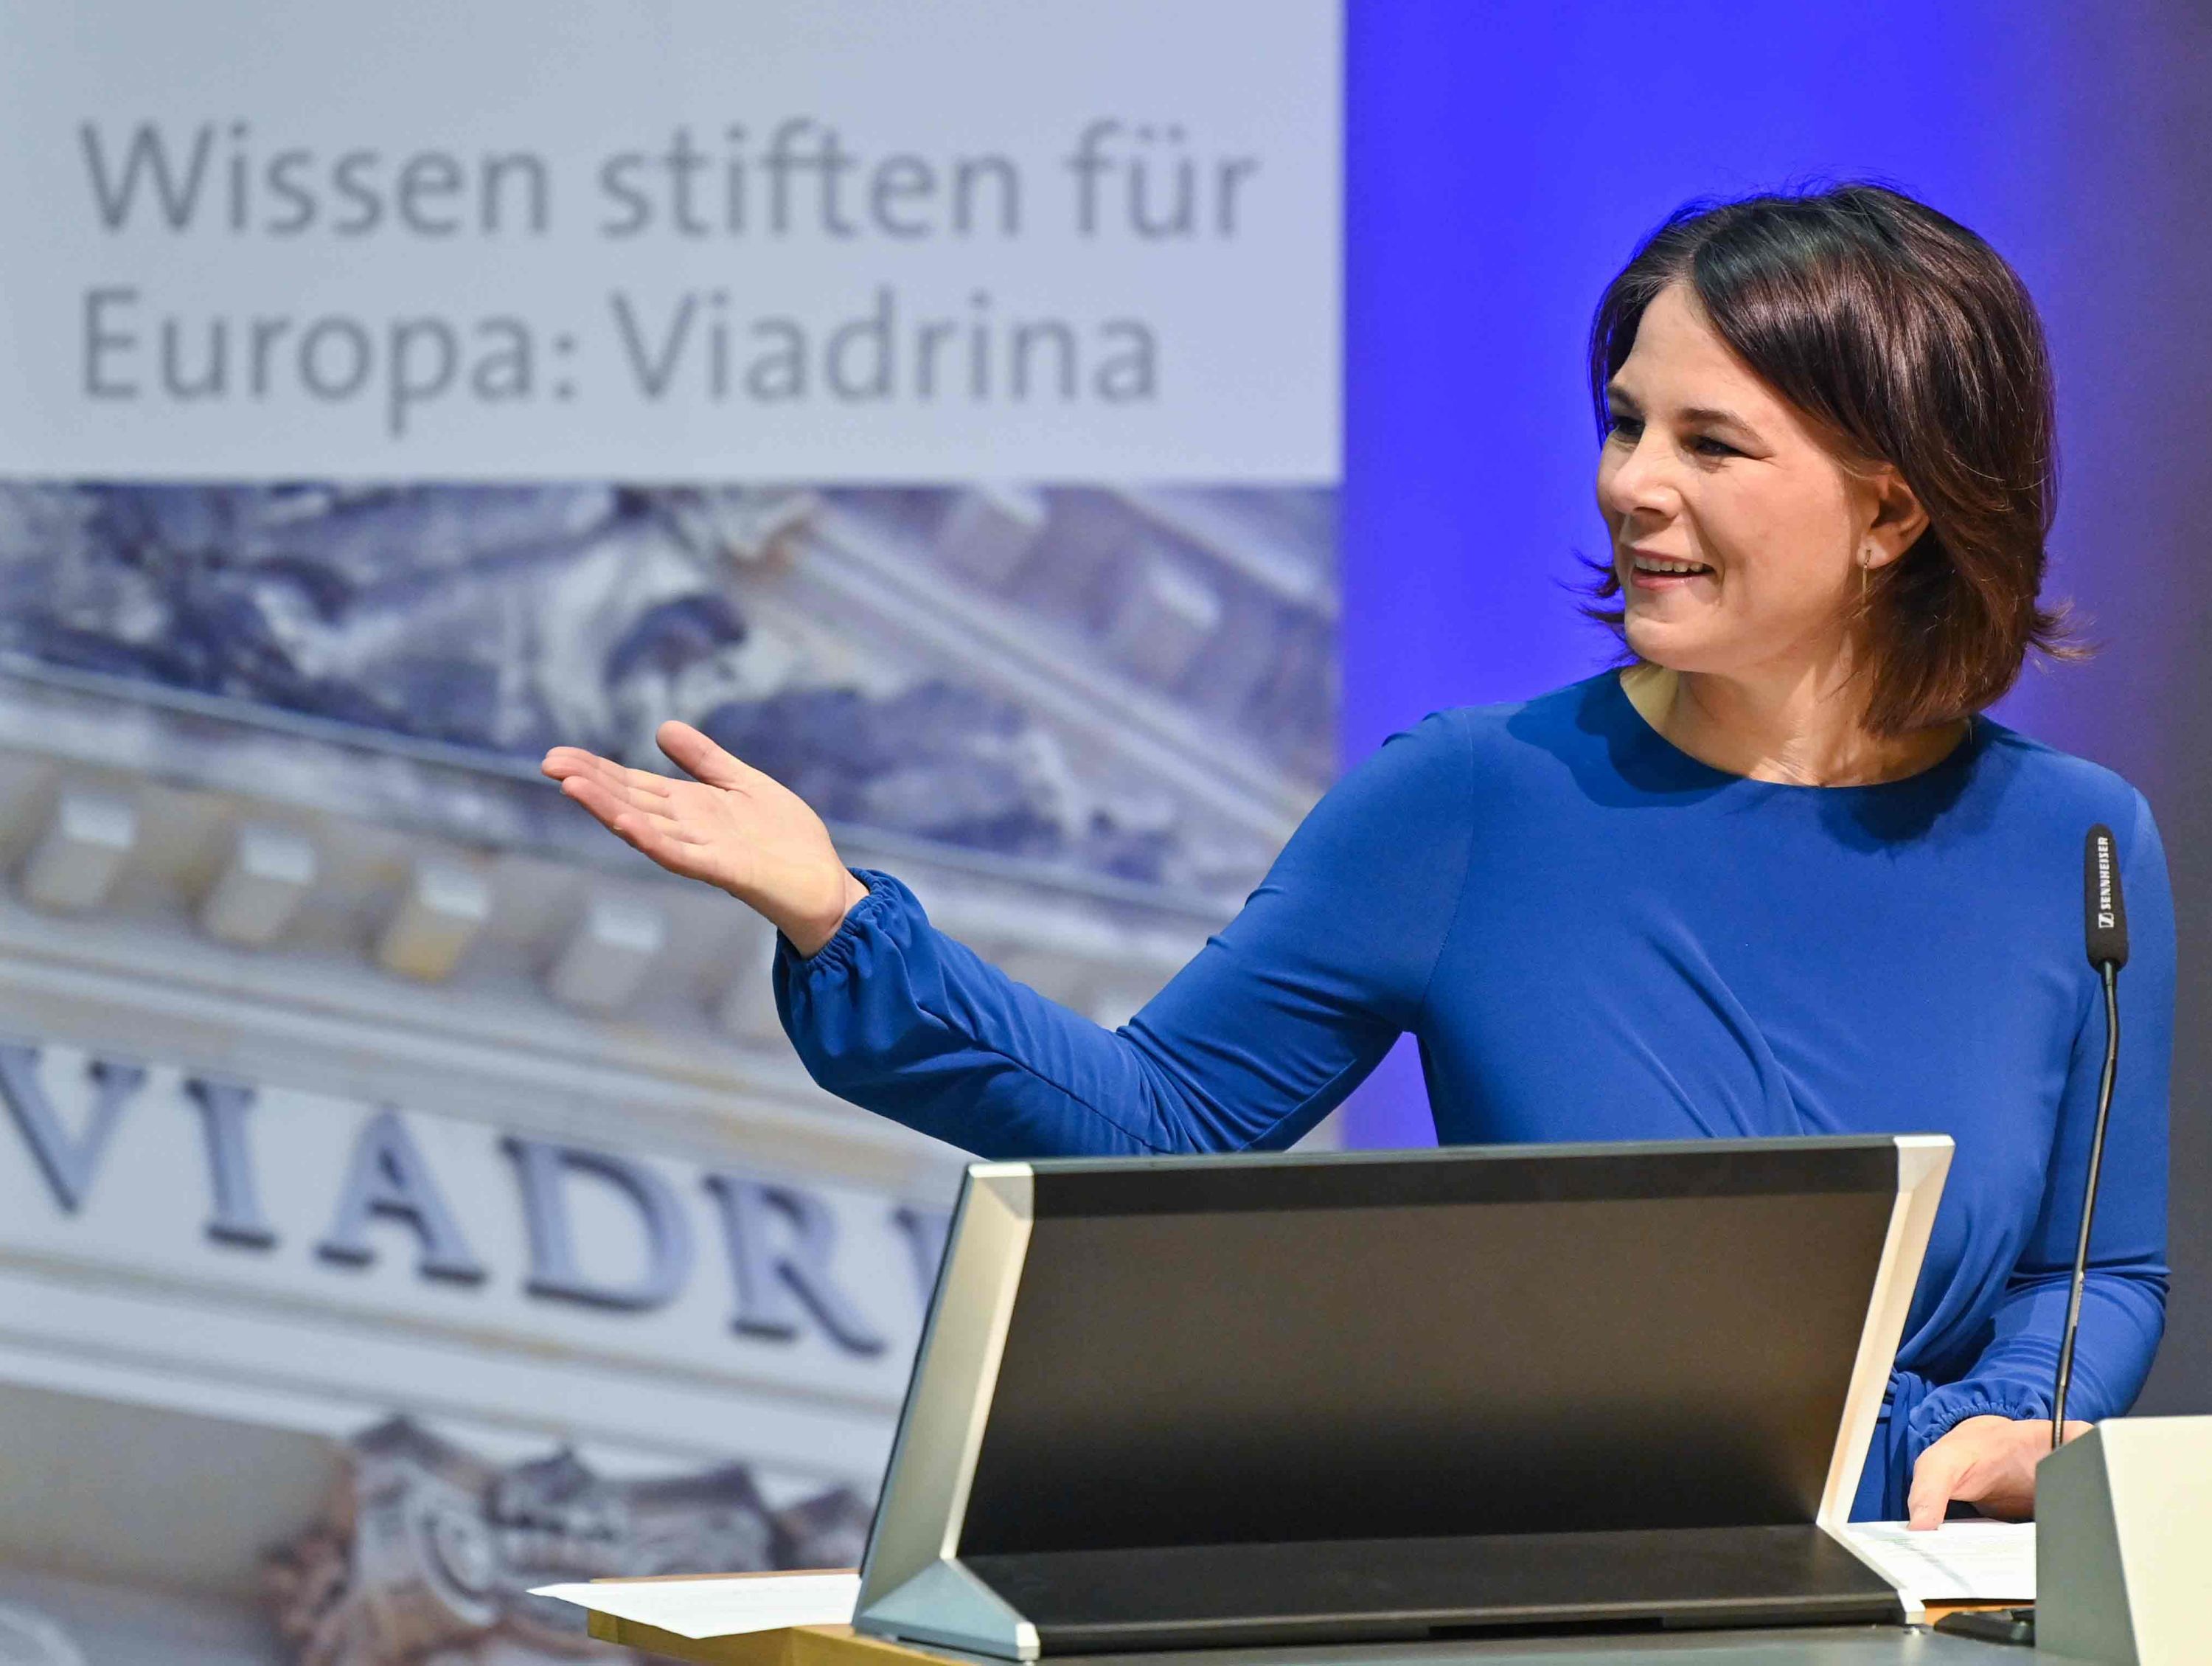
Baerbock calls for more countries to be admitted to EU

Related News

Investing

The Soviet Union Possessed The Most Sophisticated Offensive Biological Weapons Program In Human History And They Weaponized The Plague

October 7, 2026
Investing

America Doesn’t Have a Housing “Shortage” (It’s Something Much Worse)

October 6, 2026
Investing

Americans Are Spending More Because Everything Costs More

October 6, 2026
Investing

You Don’t Need Dozens of Rentals to Reach Financial Freedom (He Tried It)

October 5, 2026
Next Post
Baerbock calls for more countries to be admitted to EU

Baerbock calls for more countries to be admitted to EU

Discussion about this post

Subscribe To Our Newsletters

    Customer Support


    1251 Wilcrest Drive
    Houston, Texas
    77042 USA
    Call-832.795.1420
    e-mail – news@theinsightpost.com

    Subscribe To Our Newsletters

      Categories

      • Africa
      • Africa-East
      • African Sports
      • American Sports
      • Arts
      • Asia
      • Australia
      • Business
      • Business Asia
      • Business- Africa
      • Canada
      • Defense
      • Education
      • Egypt
      • Energy
      • Entertainment
      • Europe
      • European Soccer
      • Finance
      • Germany
      • Ghana
      • Health
      • Insight
      • International
      • Investing
      • Japan
      • Latest Headlines
      • Life & Living
      • Markets
      • Mobile
      • Movies
      • New Zealand
      • Nigeria
      • Politics
      • Scholarships
      • Science
      • South Africa
      • South America
      • Sports
      • Tech
      • Travel
      • UK
      • USA
      • Weather
      • World
      No Result
      View All Result

      Recent News

      Boxing legend Mike Tyson talks going to juvie and trading cigarettes for cookies as a young boy

      October 7, 2026

      Hogbetsotso 2026 to promote tourism, local businesses

      October 7, 2026

      Mikel Arteta’s new contract: The challenges facing Arsenal boss as he enters ‘step five’ of his project | Football News

      October 7, 2026

      Spotify expands audiobooks to over 180 markets

      October 7, 2026
      • Home
      • Advertise With Us
      • About Us
      • Corporate
      • Consumer Rewards
      • Forum
      • Privacy Policy
      • Social Trends

      Theinsightpost ©2026 | All Rights Reserved. Theinsightpost is an Elnegy LLC company, registered in Texas, USA

      Welcome Back!

      Login to your account below

      Forgotten Password?

      Retrieve your password

      Please enter your username or email address to reset your password.

      Log In

      Add New Playlist

      We are using cookies to give you the best experience on our website.

      You can find out more about which cookies we are using or switch them off in .

      No Result
      View All Result
      • Home
      • Insight
      • Blog
      • Business
      • Entertainment
      • Health
      • Politics
      • Shop
        • Gift Shop
        • Value Shop
        • Store
        • Bargain Shop
        • Discount
      • Sports
      • Tech
      • Travel
      • USA
      • Video
      • World
        • Asia
        • Africa
        • South America
        • North America
        • Europe
        • Oceania

      Theinsightpost ©2026 | All Rights Reserved. Theinsightpost is an Elnegy LLC company, registered in Texas, USA

      The Insight Post
      Powered by  GDPR Cookie Compliance
      Privacy Overview

      This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.

      Strictly Necessary Cookies

      Strictly Necessary Cookie should be enabled at all times so that we can save your preferences for cookie settings.

      Cookie Policy

      More information about our Cookie Policy

      Clear examples do more than decorate an explanation: they show how an idea behaves under recognizable conditions. In education and software documentation alike, strong illustrations begin with a defined goal, then reveal the steps, assumptions, and result without unnecessary detail. A practical test example should state the input, expected output, and boundary condition, because these elements show whether a rule works beyond the simplest case. Including a contrasting case also helps readers distinguish a valid application from a tempting but incorrect one, while concise notes explain why the outcomes differ. When examples are updated with current data and checked against the underlying rule, they remain useful across classrooms, product guides, and professional training.