After publishing The Untold Burden Of Being Your Family’s Financial Provider, I got this comment from a reader named Brian:
“I can identify with this post as I am the family CFO / CIO. I think you are WAY overcomplicating this. What is wrong with merely investing in VTI / VXUS and chill? My returns have been 12%+ for doing nothing but DCA into them every month. Going on 20+ years (mutual fund shares before ETFs) it has worked.
I realize you write a blog and invest in two ETFs and be done isn’t nearly as exciting but talk about mental load lifted! Zero mental effort into investing allocations, decision, valuations, PEs or any of that noise. I focus on tax planning and asset location. All else is supplemental but would not create very interesting content!”
Brian is right about the mental load. He might also be right about the returns. Two funds and a monthly transfer is one of the best risk-adjusted decisions a person can make, and the majority of my public equity capital sits in the S&P 500 for exactly that reason. Most professional money managers can’t beat the index. Retail investors have even worse odds.
But there’s a catch nobody mentions when they tell you to buy the index and chill. If you only own the average, you only get the average. And the average, by definition, does not get you ahead of the people you are actually competing with.
Owning The Index Means Owning The Average
Say the S&P 500 returns 12% this year. You’re up 12%. So is every other index investor you know. Congratulations, nobody moved, just like how nobody’s view improves if everybody stands up at a stadium.
The problem is that the things you want to buy with those gains are bid on by the same people who just got the same 12%. The house on a big lot in the better school district. The remodel. The private school tuition. The two weeks in Hawaii in July, when everybody else also wants to be in Hawaii in July.
Scarce assets don’t get cheaper because your portfolio went up. They get more expensive, because everyone else’s portfolio went up too.
Wealth is partly absolute and partly relative. The absolute part pays for groceries, gas, and the electric bill. The relative part decides whether you get the house on the hill with the enclosed front yard or the one two neighborhoods over with loud noises all throughout the night. Index funds pays the bills, not the luxuries.
The only way to win the relative game is to outperform the people playing it with you.
Nobody Grows Up Wanting To Be Average
Think back to when you were a kid. Did you tell yourself you wanted to be an average soccer player? An average artist? An average singer?
Of course not. You wanted to be the best at something, anything. And that instinct was healthy. Being in the top 1% of one thing does wonders for your self-esteem, even if that thing is competitive spelling or beer pong.
Then life beats it out of you. Competition gets fierce. You give up your hobbies for meetings about nothing consequential. You stop exercising because the corporate ladder demands it, and you end up heavier and unhealthier than you’d like. To numb the ennui, you spend more in the name of YOLO.
By the time you hit 60 and start thinking about retirement, you’re less healthy than you planned to be and you have far less in your 401(k) than if you’d simply maxed it out every year.
That is the average American path. Is that really the benchmark you want?
Here’s where it gets uncomfortable. The average American household is doing much better than the median one. The Federal Reserve’s Survey of Consumer Finances put average household net worth at over $1 million against a median of roughly $192,000.
That gap exists because a small number of very wealthy households drag the average up. So when someone says they’re “above average,” ask which average.
Yes, if you consistently buy an index fund for 20 years, you will crush the median American who owns almost no equities at all. The median American might be the person in those popular surveys who can’t cover a $1,000 emergency without reaching for a credit card.
But you read Financial Samurai. You know what a safe withdrawal rate is. You know what the risk-free rate is doing. Go talk to a random person about asset allocation or venture capital and watch their eyes glaze over. They’re too busy running a sub-5% savings rate and funding their lifestyle at 24% APR.
Those aren’t your competition. Comparing yourself to them is how you talk yourself into settling.
The Two Levels Of Rich
Over the past 30 years, I’ve observed two levels of rich. If you’ve decided you want to build wealth, then you must decide between the two.
Level one is the disciplined index investor. Dollar-cost average for 30 years, work until 60, retire with a comfortable nest egg and a paid-off house. This is a genuinely good outcome and I’m a fan. It’s also easier to sell.
Level two is several multiples higher. These are the people who start businesses, concentrate into individual companies, and make outsized bets. They don’t view index funds as a wealth creation engine. They view them as a place to park capital when they don’t have a better idea.
There’s no right answer here, because there’s no free lunch.
Chasing level two means accepting that you might lose a significant amount of money, time, happiness, and some of your health along the way. Every wealthy entrepreneur you admire has a story about extensive misery.
The honest framing is this: taking more risk means you will lose more often and lose bigger than the person who doesn’t. That’s the entry fee.
Why I Took The Risk
I moved to America at 14 after living in Malaysia, Taiwan, Japan, and The Philippines, and what struck me first was the abundance. Food, clean water, safe streets, a stable government. Surviving here felt easy compared to what I’d seen. I got a $4.25 an hour job at McDonald’s in high school and felt lucky I could eat all the apple pies I wanted.
But a friend died at 15, and that taught me something the abundance didn’t. Life is short and there’s no guarantee you get to enjoy a two or three decade retirement. The only hedge I could think of was to study harder, work harder, save more, and invest more aggressively than average.
FIRE was in my head by 1999, my first year in finance. I knew I couldn’t survive 60-hour weeks for two decades, which meant I had to take more risk to compress the timeline.
So I did.
In 2000, I bought a speculative Chinese internet company called VCSY that ran up 50X and then went to zero when the dot-com bubble collapsed. I took what was left of those proceeds and bought a $580,500 condo in 2003 with a $464,000 loan. Two years later I levered up again and bought a $1.5 million house with a $1.2 million mortgage, without selling the condo.
Looking back, that was an insane amount of leverage for a 28-year-old. But I believed San Francisco real estate was good value, and I wanted enough passive income to walk away by 40. Today, I still think San Francisco real estate is some of the cheapest in the world compared to how much income and wealth you can build.
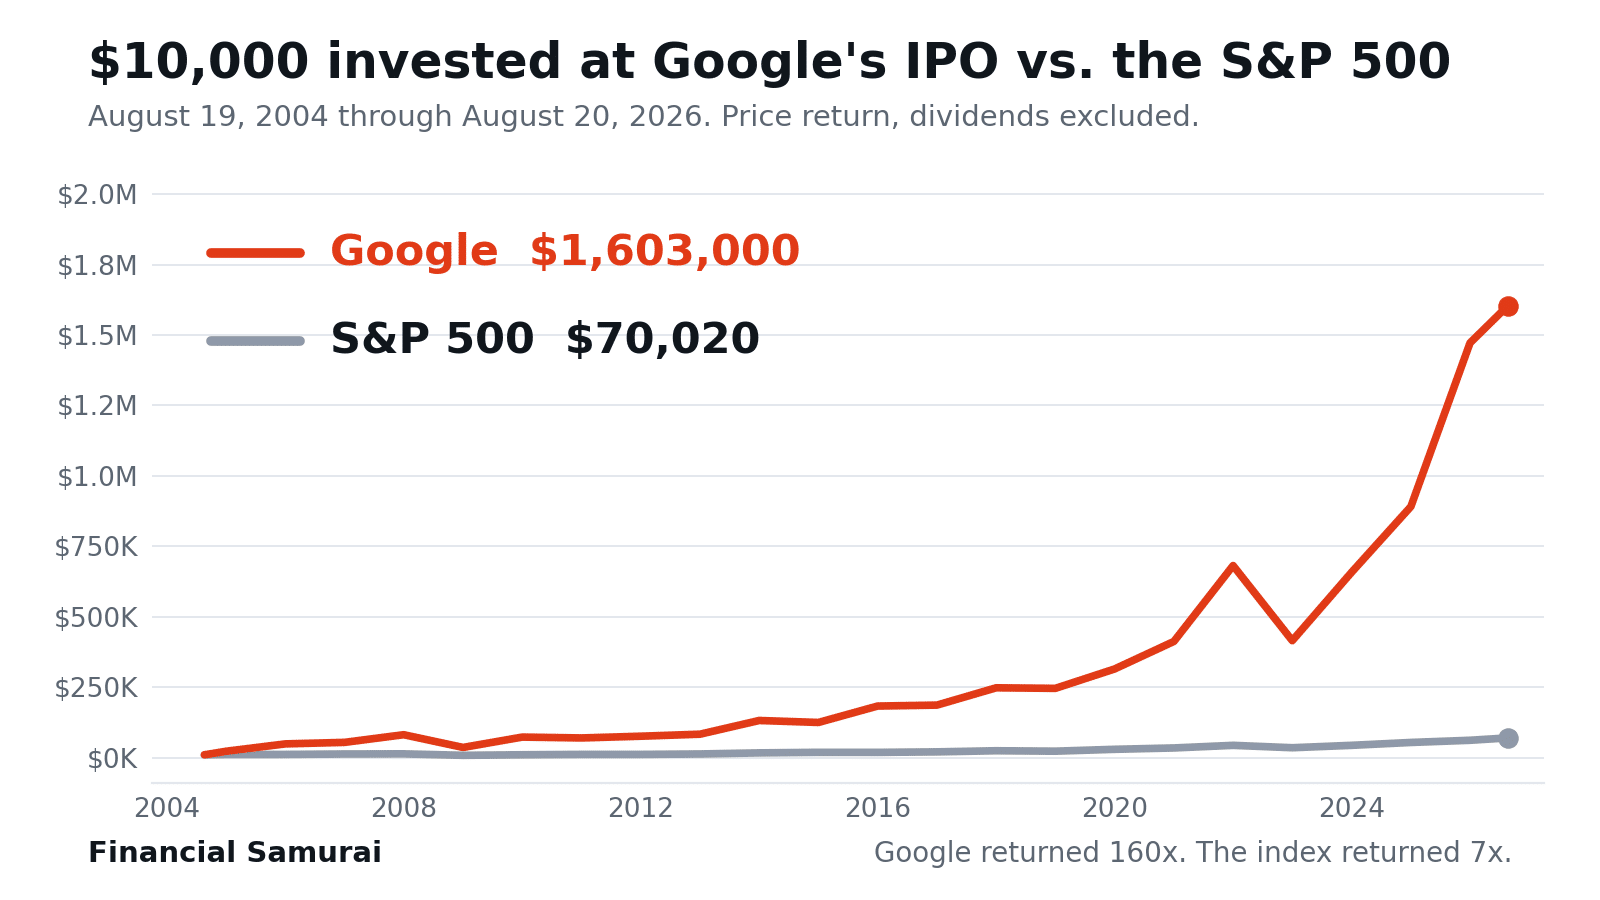
I reinvested 90% to 100% of the 50% – 70% I was saving each year into risk assets. Most of it went into San Francisco property and growth stocks like Google, Apple, and Tesla, not the S&P 500. When things were good the portfolio flew. When things were bad it hurt like hell.
There is no version of this where I retire in 2012 at 34 by buying the index and chilling. Maybe by 55, but definitely not by 34.
Dial Risk Down Once You’ve Made It
Once you’ve broken free, or built enough that your spouse can, that’s when you reduce risk. Shift more capital into index funds. Buy individual Treasury bonds and lock in the risk-free rate. Stop needing to hit triples and home runs.
But here’s the irony. Because you already have enough, you can also afford to take more risk at the margin. The constraint isn’t the math, it’s your sleep. If a position has you refreshing quotes all throughout the day when you’re supposed to be present with your children, you’ve taken the wrong size and you’ve got the point of financial independence backward.
Right now I prefer the risk-reward on VCX in the high $30s to the S&P 500 after a roughly 13% run. I’d guess the S&P 500 finishes the year somewhere between up 5% and up 20%, which is down 8% or up 7% from here.
VCX I could see going from $38 down to $28 or up to $60 by year end. That’s a 26% drawdown against a 58% gain. As a rational capital allocator with idle cash and the stomach for volatility, I’d rather own the asymmetry. I want to benefit from any potential Anthropic IPO frenzy.
If I’m wrong, I lose money or I make less than I would have. That is the entire downside, and I’ve already accepted it.
Everything Is Rational In The End
Brian isn’t wrong. He’s optimizing for peace of mind, and peace of mind is worth a lot. I’d never argue someone out of an S&P 500 index ETF.
But don’t confuse a low-effort strategy with a high-return one. Investing in index ETFs will make you comfortable. It will rarely make you exceptional, because you’re buying the exact same thing as everybody else you’re bidding against.
The question isn’t which portfolio is correct. It’s which trade-off you actually want. Less risk and a predictable average, or more risk and a shot at above average, with the very real chance you end up below it.
When it comes to money, I’ll take the calculated risk every time I think the odds are in my favor.
Readers, where do you land? Is index-and-chill enough for you, or are you still hunting for level two wealth? What’s the riskiest financial bet you’ve ever made, and did it work out? And for those of you who’ve already reached financial independence, did you dial risk down or dial it up?
Protect The People Who Didn’t Choose Your Risk Tolerance
Taking more risk only works if a bad outcome doesn’t take your family down with it. I levered into a $1.5 million house at 28 with a $1.2 million mortgage. If something had happened to me that year, my wife would have inherited a hefty $6,800/month payment, not a portfolio.
That’s the difference between calculated risk and reckless risk. Calculated risk has a floor under it.
Term life insurance is the cheapest floor money can buy, and it’s what lets you concentrate, lever up, and swing at level two wealth without gambling with people who didn’t sign up for it. Check your rates on Policygenius. It takes a few minutes and the quotes are free. I locked in a 20-year term policy during a refinance and my stress level dropped more than any asset allocation change ever did.
Invest In The Physical Side Of The AI Boom
If you want exposure to the biggest capital cycle of our lifetime without picking a single stock, look at where the money physically lands. AI is a general-purpose technology, and general-purpose technologies need infrastructure. Compute has to sit somewhere, drawing power, on real land.
Hyperscalers are spending hundreds of billions a year on that buildout, and McKinsey pegs the total need at roughly $7 trillion by 2030. The binding constraint isn’t chips. It’s power and permitting.
That’s a real estate story dressed up as a technology story. Fundrise gives you access to that side of the trade with a low investment minimum. I’ve invested over $300,000 with Fundrise, and it’s the passive way I get exposure without becoming a landlord again. Fundrise is a long-time sponsor of Financial Samurai.
Discussion about this post