Maximizing Your Cash: An Analysis of High-Yield Savings Accounts and Treasury Money Market Funds
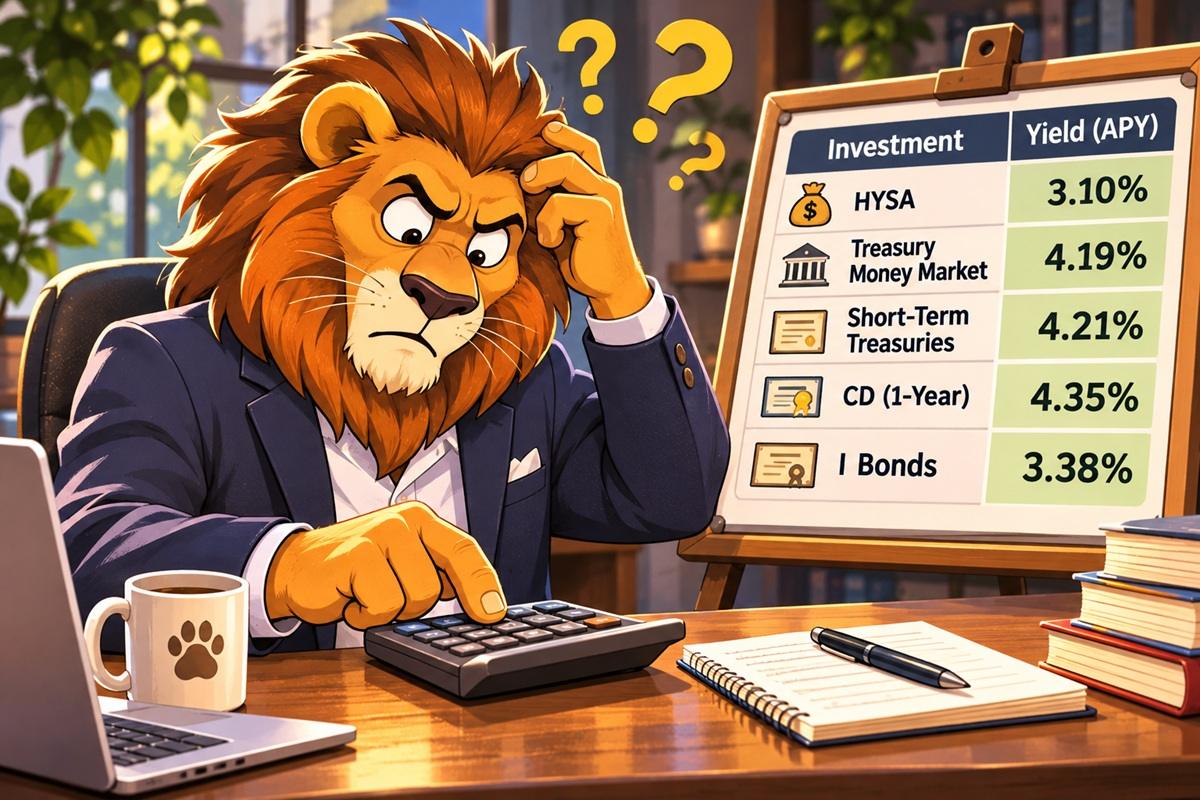
When evaluating where to allocate your funds, it’s important to note that the account with the highest stated interest rate may not be the most lucrative choice.
High-yield savings accounts (HYSAs) and Treasury money market funds are both valuable options for storing your savings. However, they are subject to different tax treatments, which can significantly influence your overall returns based on your tax profile.
To assist in making a more informed choice, our Tax-Equivalent Yield Calculator allows you to assess and compare the post-tax returns of these two investment vehicles.
Using the Calculator
To begin using the calculator, input the amount you intend to save or invest, the interest rate of your chosen high-yield savings account, and the yield of a Treasury money market fund.
Next, provide your federal marginal income tax rate along with your combined state and local tax rates. You also have the option to specify the percentage of the Treasury fund’s income that is tax-exempt at the state level.
The calculator will generate the following:
- After-tax HYSA yield: The effective annual yield on your high-yield savings account when accounting for federal, state, and local taxes.
- After-tax Treasury money market yield: The effective annual yield on the Treasury fund, taking into consideration any state and local tax exemptions.
- Tax-equivalent yield: The yield needed from a fully taxable savings account to match the Treasury market fund’s after-tax return.
- Annual dollar difference: The additional earnings you could realize each year by choosing one option over the other based on your investment amount.
This tool simplifies the comparison process, allowing for a clearer understanding of the after-tax benefits associated with each option.
Understanding the Tax Implications
Interest accrued in high-yield savings accounts is subject to federal income tax as well as any relevant state and local taxes.
Conversely, interest earned from U.S. Treasury securities is taxable at the federal level but generally exempt from state and local taxes.
Treasury money market funds primarily invest in short-term Treasury securities and other highly liquid instruments. Depending on the specific holdings of the fund, a portion or all of the income generated may be eligible for state and local tax exemptions.
For example, consider the following scenario:
- A high-yield savings account offering a 4.00% APY.
- A Treasury money market fund yielding 3.80%.
- A federal marginal income tax rate of 24%.
- An 8% combined tax rate for state and local income taxes.
Assuming that the entire income from the Treasury fund is exempt from state and local taxes, the estimated after-tax yield for the HYSA would be approximately 2.72%, whereas the Treasury fund’s yield would be 2.89%.
The tax-equivalent yield for the Treasury fund would be around 4.25%. This means that to match the Treasury fund’s after-tax return, a high-yield savings account would need to offer a yield of 4.25%.

Discussion about this post