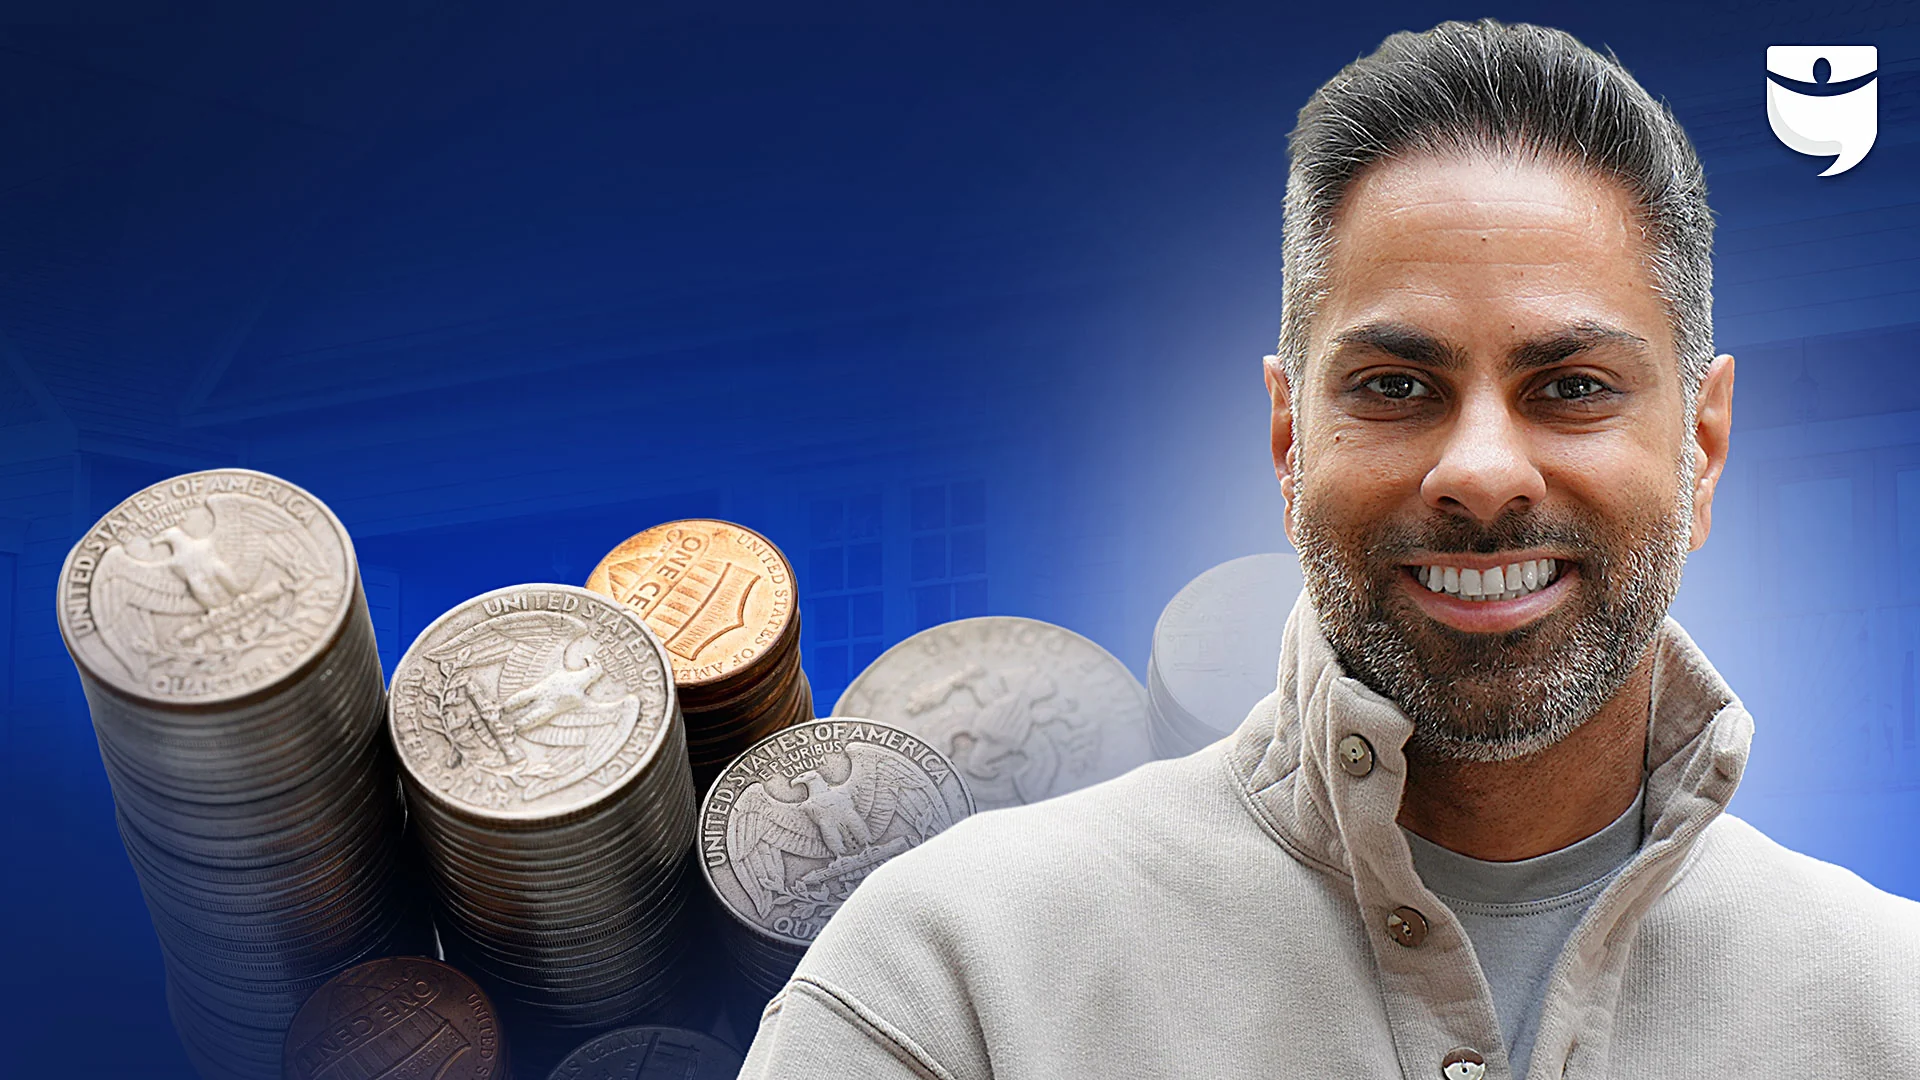
The Contrarian Approach to Finance: Ramit Sethi’s Strategies
Ramit Sethi has defied conventional financial wisdom: opting to rent rather than buy, purchasing new luxury cars, indulging in lavish vacations, all while successfully accumulating millions. Amidst a climate of economic uncertainty, Sethi asserts that there is still a path to financial empowerment: automating your savings, investments, and expenditures.
Meet Ramit Sethi
Ramit Sethi is a prominent figure in the realm of personal finance, known for his bestselling book I Will Teach You To Be Rich and the Netflix series How to Get Rich. He also hosts the Money for Couples podcast, making him a trusted voice for those looking to optimize their financial standing.
A Collaborative Financial Vision for Couples
Understanding that many couples face financial disconnection, Sethi has created a methodology that empowers partners to collaboratively create their ideal lifestyle—be it luxurious vacations, upscale cars, or simply enjoying a night out. Achieving this lifestyle hinges on getting four critical personal finance metrics in order, which he is set to reveal.
The Merits of Renting Over Owning
Throughout the conversation, Sethi shares his rationale for continuing to rent, despite societal pressures advocating for homeownership. He emphasizes that housing is becoming increasingly unaffordable for many, especially in high-cost areas. Sethi also discusses a prevalent financial mistake couples often make, which can jeopardize both their financial future and relationship satisfaction.
Understanding the Current Economic Landscape
Addressing the economic climate, Sethi describes it as confusing and acknowledges the struggles many face today with soaring housing prices and rising interest rates. Yet, he believes there are still opportunities for those willing to utilize established financial strategies.
Financial Education and Personal Accountability
A common thread Sethi recognizes among those he consults is a lack of financial literacy. Surprisingly, he finds that the majority of individuals have never engaged with personal finance literature. For him, empathetic understanding toward the challenges younger generations face is vital, especially when considering the systematic barriers to homeownership.
Automating Financial Success
When it comes to savings and investments, Sethi advocates for automation. He encourages individuals to think systematically about their financial planning rather than engage in frugal micromanagement. By automating savings and investing in index funds, one can more effectively build wealth without the constant stress of tracking every expense.
Identifying Key Financial Metrics
Sethi argues that understanding four key financial numbers is essential: your fixed costs, savings rate, investment contributions, and guilt-free spending allowance. He asserts that this approach simplifies financial planning and helps individuals feel more in control of their money.
The Significance of Meaningful Spending
While saving money is important, Sethi emphasizes the need to spend meaningfully on things that truly matter. He believes that living a life of abundance doesn’t require marginalizing your spending choices; instead, it involves allocating resources towards experiences and items that bring joy.
Encouraging Open Financial Dialogue in Relationships
Sethi presents strategies for couples to engage in meaningful financial discussions. He suggests that rather than fixating on numbers and spreadsheets, partners should share their visions for a rich life. This involves understanding each other’s dreams and aspirations, ultimately leading to a more harmonious financial partnership.
Conclusion
As Sethi concludes, he reiterates the importance of running the numbers when making significant financial decisions, particularly regarding homeownership. He argues for informed choices rather than succumbing to societal norms. Whether it’s renting or owning, ensuring that financial decisions align with personal goals is key to building a fulfilling, rich life.

Discussion about this post