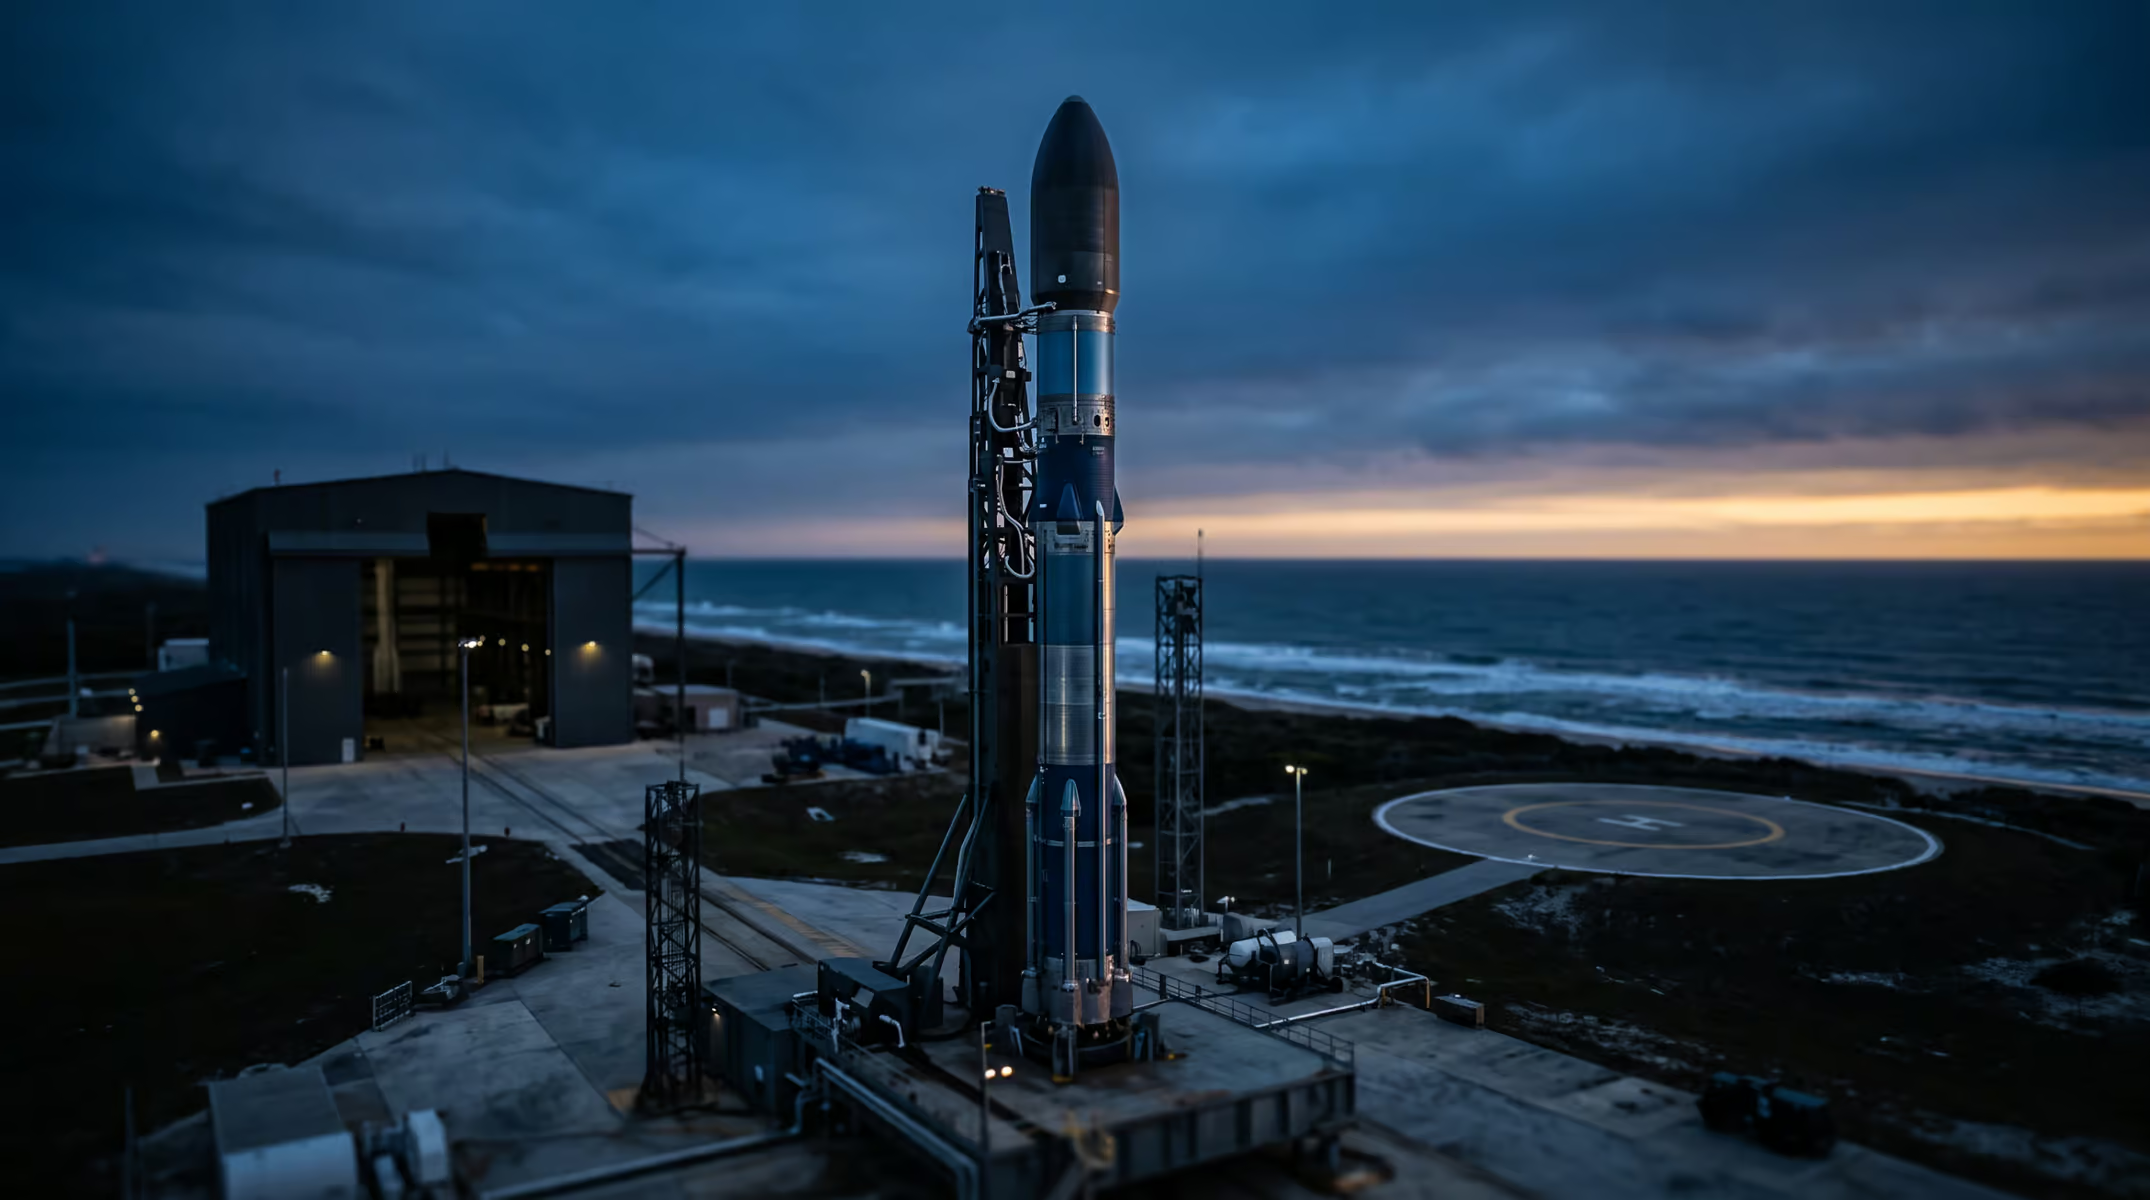
Rocket Lab Posts Significant Q3 Growth Amid Neutron Delays
KEY INSIGHTS
- Rocket Lab’s revenue in Q3 surged by 73% to $267.8 million, exceeding its guidance range.
- The company’s backlog reached approximately $3.6 billion, marking a 52% increase since June, while the first flight of the Neutron rocket is now projected for 2027.
- As of November 9, Rocket Lab’s stock closed at $58.86, remaining 61% below its 52-week high of $151.
On November 9, Rocket Lab Corporation (RKLB) announced its third-quarter financial results, revealing a backlog of around $3.6 billion, a notable increase of 52% compared to June. Revenue hit $267.8 million, reflecting a 73% year-over-year growth that surpassed the company’s own forecasts.
The stock initially rose 10.9% to close at $58.86, but dipped approximately 6.5% in after-hours trading to $55.02. Compared to its peak of $151, the stock’s current valuation presents questions regarding market assumptions.
Q3 Revenue Surpasses Guidance with 73% Growth
Revenue figures reached $267.8 million, climbing from $155.1 million a year earlier. In August, management had anticipated revenue between $250 million and $265 million, whereas analysts had estimated around $257.2 million. The company outperformed Street expectations by 4.1%, with product revenue at $197.5 million and services contributing $70.3 million.
The quarterly margins presented a mixed bag. The GAAP gross margin stood at 33.6%, surpassing the company’s projection of 29% to 31%, although it declined from 37.0% the previous year. Adjusted EBITDA recorded a loss of $18 million, which aligns with expectations and shows an improvement from last year’s loss of $26.3 million.
However, net losses reached $79.7 million, or $0.12 per share, compared to a loss of $18.3 million, or $0.03, from the prior year, which exceeded analyst expectations. While last year’s results benefited from a significant tax gain, this year’s losses underscored challenges for the company.
Backlog Experiences 52% Growth to $3.6 Billion
As of September’s end, Rocket Lab’s backlog totaled approximately $3.6 billion, increasing from $2.36 billion in June. Notably, about 52% of this backlog is associated with launches, while space systems account for the remaining 48%. Moreover, the company signed new contracts valued at approximately $1 billion, alongside $470 million designated for space systems.
Approximately 32.9% of the backlog is anticipated to convert into revenue within the next year, equating to about $1.2 billion of scheduled work. The fourth-quarter revenue forecast ranges from $270 million to $290 million, with adjusted EBITDA losses projected between $14 million and $20 million.
Neutron’s First Flight Delayed to 2027
Management recently announced a delay of the first launch of Neutron to no earlier than 2027, following the discovery of issues with propellant tanks. This announcement affected the stock price, which declined significantly in the days following the update, reaching a low of $45.99 before recovering to $58.86 as of November 9.
This delay poses two main concerns: the timeline for achieving positive adjusted EBITDA following a successful flight and maintaining demand, with 16 missions already booked. The long-term outlook remains promising if these challenges are effectively addressed.
Valuation Analysis of Rocket Lab’s Stock
With approximately 681 million basic shares projected for Q4, Rocket Lab’s market valuation stands at about $40.1 billion. After deducting $4.70 billion in cash and securities, the enterprise value is around $35.4 billion, equating to roughly 32 times the anticipated fourth-quarter revenue.
| Scenario | 2030 Revenue | Sales Multiple | Required Growth (2026-2030) | Value per Share |
|---|---|---|---|---|
| Bear | $2.0 billion | 5x | 20% per year | $10.88 |
| Base | $3.5 billion | 8x | 38% per year | $27.41 |
| Bull | $5.5 billion | 12x | 55% per year | $62.31 |
To achieve a 12% annual return from the current price, Rocket Lab would need to target approximately $7.8 billion in revenue by 2030. Analysts have set a more optimistic average price target of $102.15, with strong buy recommendations from most of them, predicated on successful Neutron operations and earnings from Iridium.
Identifying Risks Ahead
Current financial health appears stable, with Rocket Lab holding approximately $4.70 billion in cash and securities, alongside a positive operating cash flow. However, the rising share count remains a concern, having notably increased this year due to capital needs.
The pending acquisition of Iridium Communications Inc. adds another layer of complexity, with regulatory approvals still outstanding and no specified closing date. If completed, this deal would likely dilute shares further, impacting investor sentiments.
Upcoming Checkpoints for Investors
Investors should watch for the upcoming fourth-quarter revenue results, which need to fall within the $270 million to $290 million range, along with stable gross margins. A firm launch schedule for Neutron will also be critical, as delays could further affect stock perceptions.
With a robust backlog, Rocket Lab may have sufficient momentum while awaiting Neutron’s launch, but any additional delays could distort the current market evaluation of the stock.
This article is for informational purposes only and should not be considered financial or investment advice. The author does not hold positions in any of the mentioned securities. Always consult with a licensed financial advisor before making investment decisions.


Discussion about this post